What happened
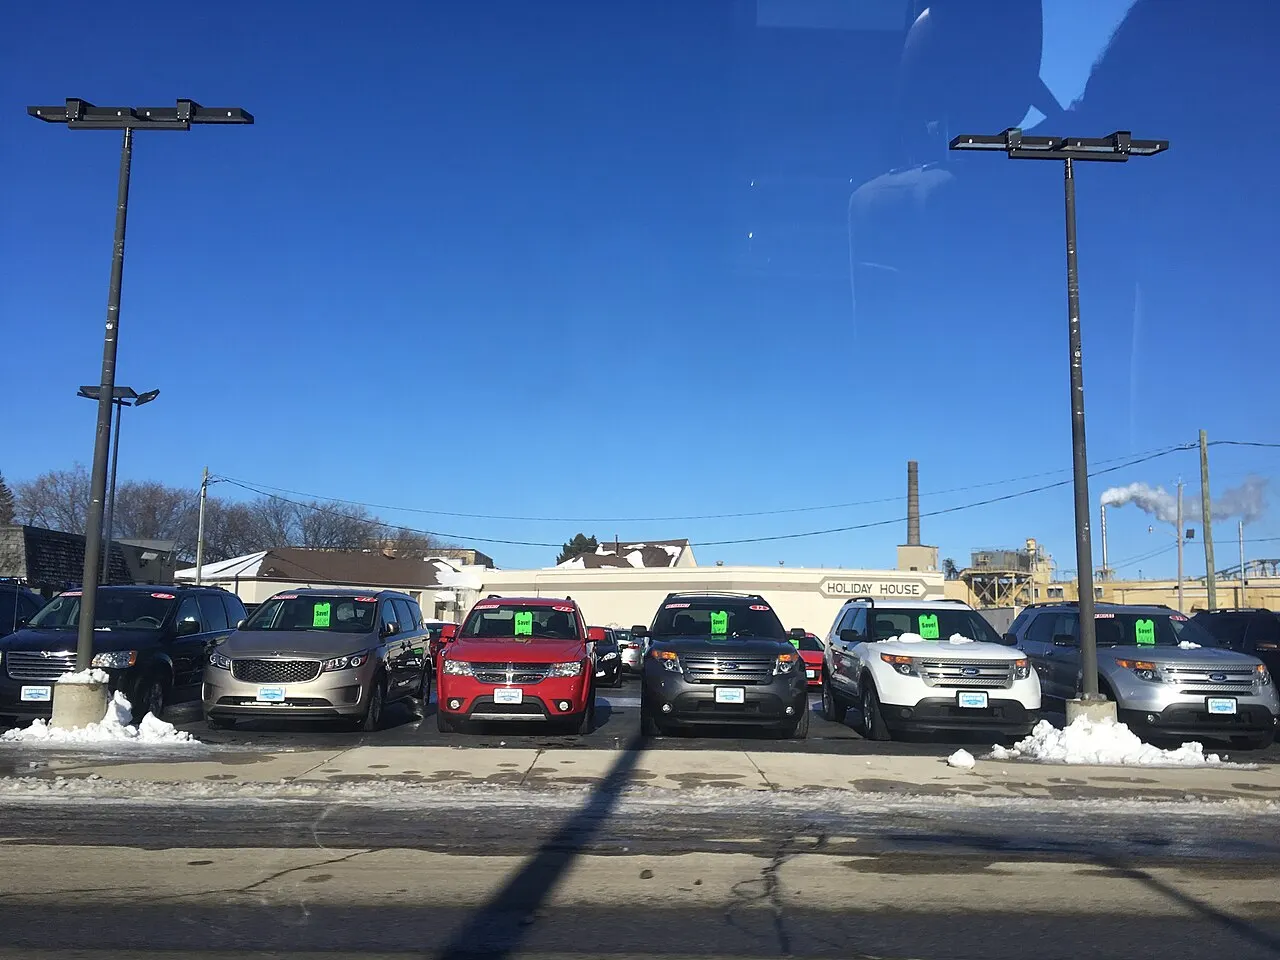
A new car in the United States has never cost this much. Kelley Blue Book says the average transaction price hit $51,109, a record high, in a report released Tuesday. That is about $500 above the previous record, set in December 2025.
The number is what buyers actually paid, not the sticker price. It adds the cost of extra features and subtracts dealer discounts and other incentives. It covers every kind of new vehicle, from small sedans to full-size pickups and electric cars, and every major brand, including Toyota, Subaru, Tesla and Mercedes-Benz.
There is one small piece of good news in the report. Prices are still rising, but more slowly. The $51,109 average is up 2.1% from a year ago. Erin Keating, an executive analyst at Cox Automotive who co-wrote the report, said that pace is actually below inflation. For comparison, new car prices rose an average of 3.4% a year between 2012 and 2021.
Why it matters
Few purchases hit a household budget like a car. Most Americans buy one only every few years, so the jump can come as a shock. And the price on the window is only part of the bill.
Borrowing costs make it worse. Auto loan rates now run over 7% for new vehicles and about 11% for used ones, according to Edmunds. Keating said more of each monthly payment now goes to interest instead of paying down the loan.
Used cars offer no escape. The average used car now costs close to $27,000, up 6% from last year, according to Cox Automotive. Cars priced below that are a "sliver" of the market, said Ivan Drury, director of industry insights at Edmunds. Used sales make up about two-thirds of all car sales, so the squeeze reaches most buyers.
The roots go back to the pandemic. A semiconductor shortage meant fewer cars were built, and carmakers chose to build their most profitable models first. That left fewer used cars entering the market in the early 2020s, and inventory is still thin today.
Financing has stretched to keep monthly payments down. Edmunds found buyers took out loans averaging $44,664 in the past quarter, the most ever. More than a quarter of buyers signed up for loans of 84 months or longer, often with down payments of $500 or $1,000. Drury said that combination gets expensive fast at today's interest rates, especially for first-time buyers with no trade-in to soften the blow.
What it means for the US
This is a household-budget story as much as a car story. When the average new vehicle costs $51,109 and the average loan tops $44,000, a car payment competes with rent, groceries and everything else. [Gas prices dipped below $4](/article/gas-prices-dip-below-4-inflation-stubbornly-high) this week, but broader inflation is still running hot, so relief at the pump does not offset the cost of the car itself.
Tariffs are part of the price. The report points to tariffs on steel and aluminum and on goods imported from Canada, which matter because American automakers build vehicles on both sides of the border. Copper for wiring and computer chips for sensors and electronics have also gotten pricier, in part because data centers are competing for the same supplies. The same trade tensions behind the tariffs also drive the [US-China chip war](/article/us-china-chip-war-explained), which keeps semiconductor supply tight.
The shift is also cultural. Americans keep buying bigger vehicles, and carmakers keep building them. The average full-size pickup now carries a sticker price near $72,000, according to Kelley Blue Book. Compact sedans have largely disappeared from showrooms because they earn carmakers less money. Mike Wall, an analyst at Mobility Global, said small cars were "sort of that loss leader" that got buyers in the door. Buyers have also grown used to features that cost extra: 360-degree cameras, heated seats, parking assist. "No one wants entry-level anymore," Drury said. "Everybody goes mid-to-upper trim levels."
What happens next
The market is not growing. About 16 million Americans buy a new car each year, roughly a million fewer than before the pandemic. Fewer buyers in their late 30s and early 40s are shopping at all; Keating said that age group is holding onto cars longer while household budgets stay tight. Buyers now skew older and wealthier, with more drivers aged 65 and up buying than ever before.
That leaves automakers fighting over a pie that is not getting bigger. "They're stealing share from their competitors as opposed to counting on more consumers entering the picture," Keating said. Electric vehicles are no rescue yet: they make up about 6% of new cars sold, according to Edmunds, even after years of heavy investment.
For buyers, the near-term picture is more of the same: high prices, high borrowing costs, and longer loans. The one trend working in their favor is the slower pace of price growth.